
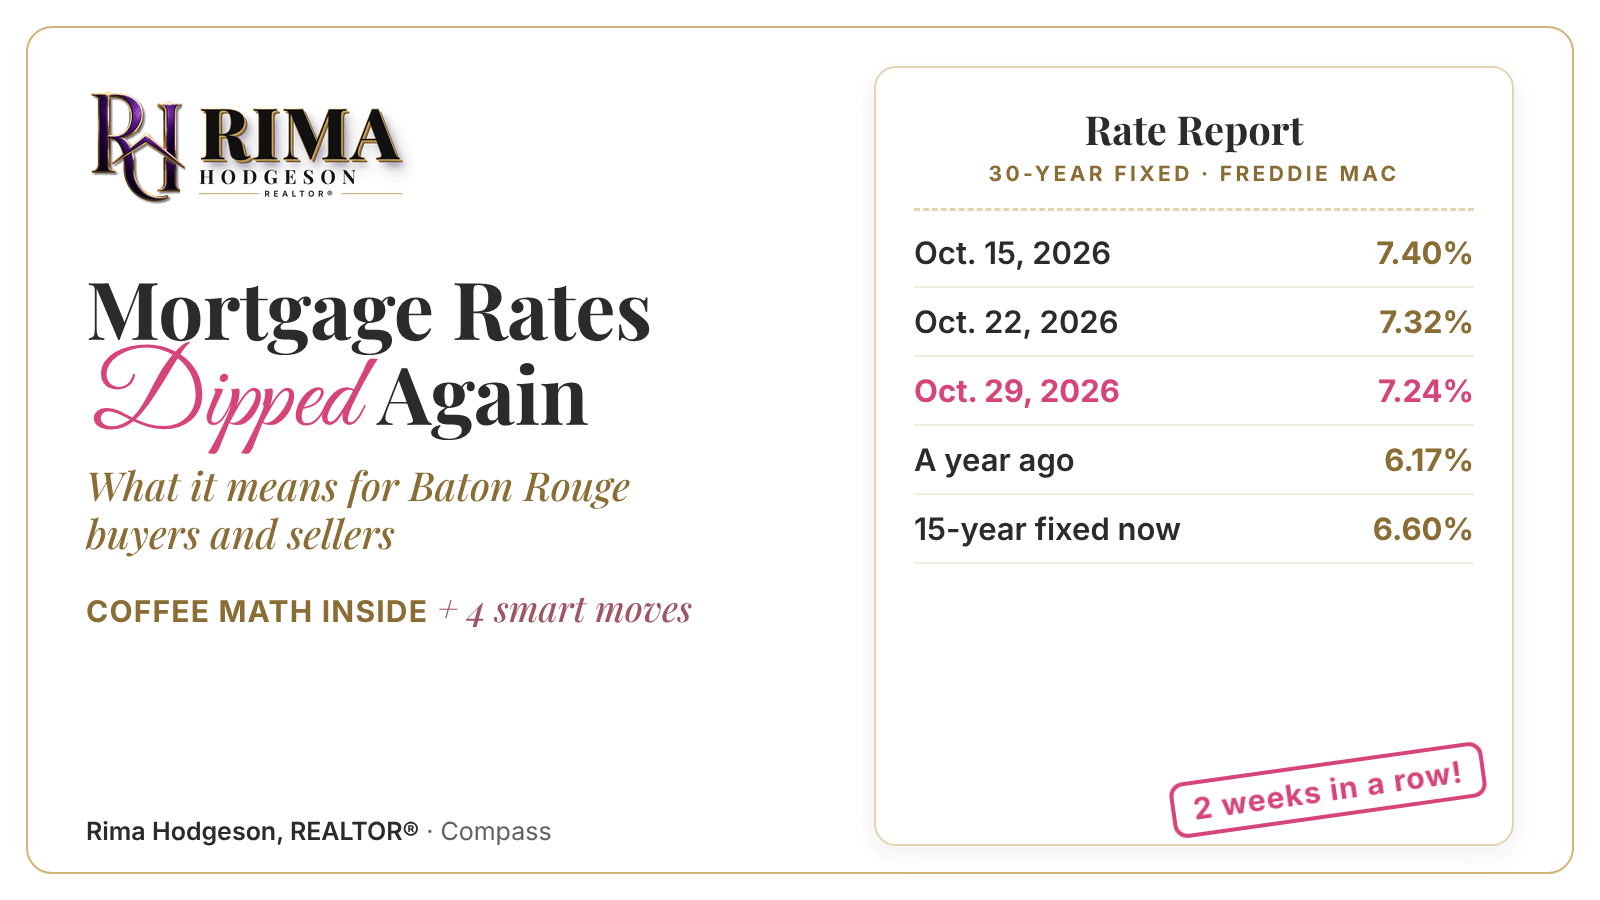

Good news, y'all: mortgage rates went down again. That makes two weeks in a row.
So what does a small dip really mean for a monthly payment here in Baton Rouge? I grabbed my calculator (and a cup of coffee) to find out. Let's dig in.
The quick answer: The average 30-year fixed mortgage rate fell to 7.24% on Oct. 29, down from 7.32% the week before and 7.40% on Oct. 15 (Freddie Mac). On a typical $269,000 Baton Rouge home with 10% down, that's about $26 a month less than on Oct. 15. Rates are still about 1 point higher than a year ago, so a good plan matters more than perfect timing.
Jump to:
Rates right now Coffee math Why rates move What's next If you're buying If you're selling
What Are Mortgage Rates Right Now?
What is the average mortgage rate right now? Every week, Freddie Mac surveys lenders across the country and shares the average rates. Here's the newest:
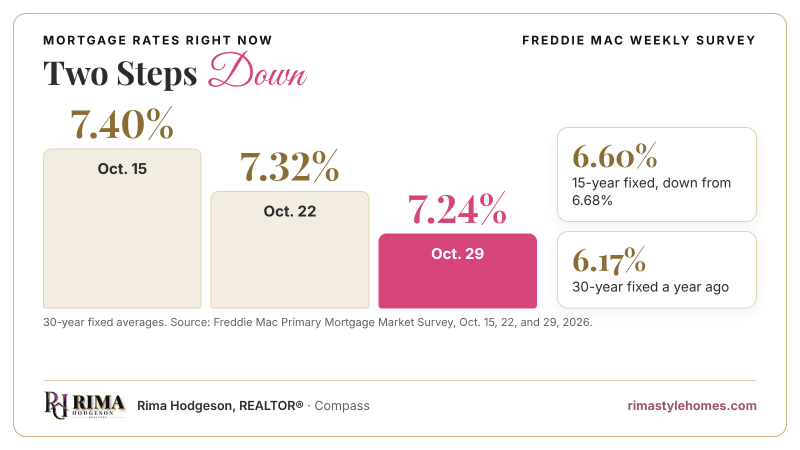
- 30-year fixed: 7.24% on Oct. 29, down from 7.32% on Oct. 22 and 7.40% on Oct. 15
- 15-year fixed: 6.60%, down from 6.68% on Oct. 22
- A year ago: the 30-year fixed was 6.17%, and the 15-year was 5.41%
That's the lowest 30-year average in more than a month. Freddie Mac's chief economist says the drop is "modestly boosting purchasing power" for buyers. In plain words: your money stretches a little further than it did in mid-October.
Keep in mind, these are national averages. Your own rate depends on your credit, your down payment, the type of loan, and more. A lender can give you your real number.
What Does the Dip Mean for a Baton Rouge Payment?
How much does a lower rate save on a Baton Rouge home? Let's use the September 2026 median sale price for the Greater Baton Rouge area: $269,000 (Greater Baton Rouge Association of REALTORS®). With 10% down, you'd borrow $242,100.
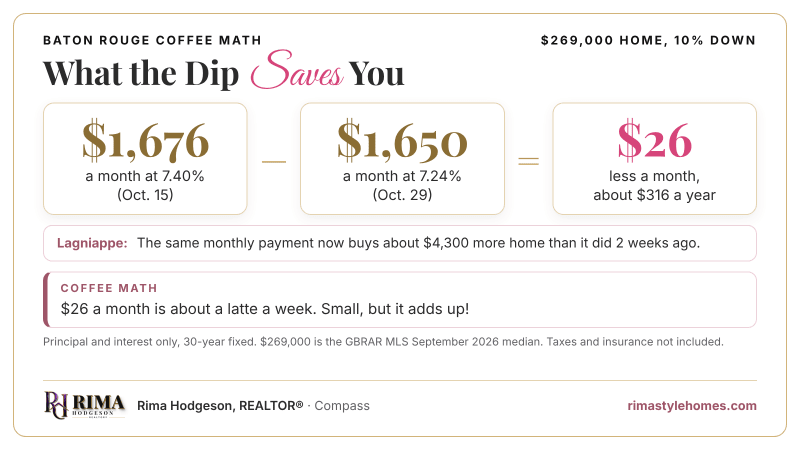
- At 7.40% (Oct. 15): about $1,676 a month
- At 7.24% (Oct. 29): about $1,650 a month
- The difference: about $26 a month, or about $316 a year
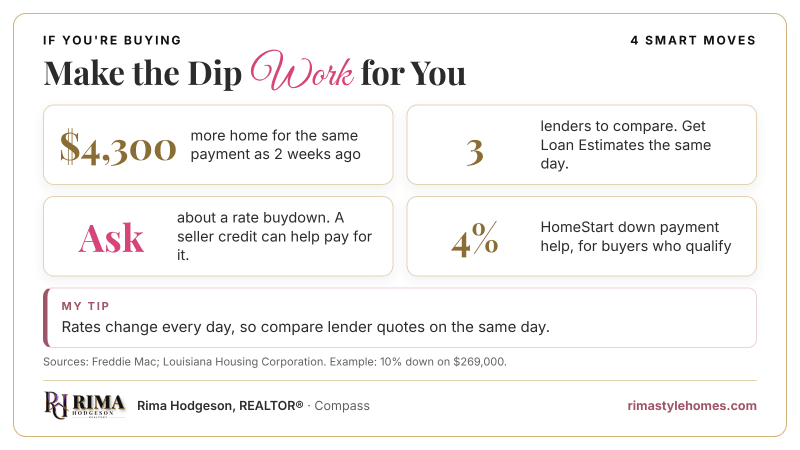
That's about a latte a week. Here's the bigger lagniappe: if you keep the same monthly payment, the lower rate lets you buy about $4,300 more home than you could on Oct. 15.
These numbers are principal and interest only. Property taxes, homeowners insurance, and flood insurance (if you need it) come on top. I broke those down in Surprise! The Home-Buying Bills Nobody Warns You About.
Why Did Mortgage Rates Go Down?
Does the Federal Reserve set mortgage rates? No, and that surprises a lot of people! On Oct. 28, the Federal Reserve left its key rate where it was. Most people expected that, so mortgage rates barely reacted.
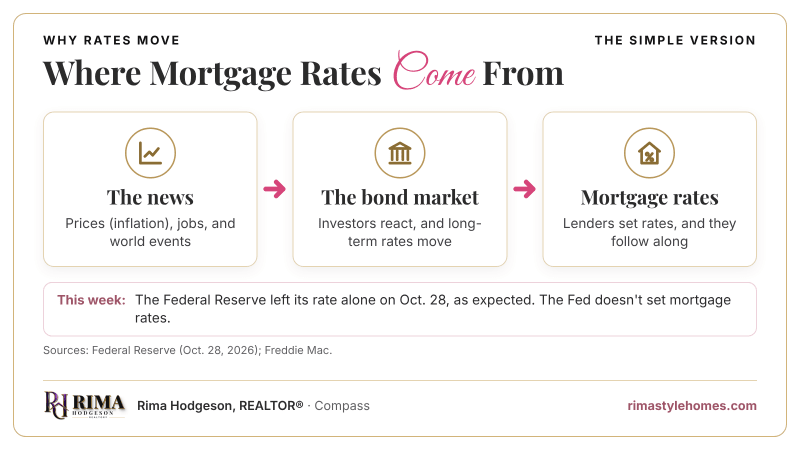
Mortgage rates follow the bond market. When investors react to news about prices (inflation), jobs, and world events, long-term rates move, and mortgage rates follow along. Next, experts are watching new reports on inflation, the economy, and jobs.
Will Mortgage Rates Keep Going Down?
Will mortgage rates drop in 2027? The truth? Nobody knows for sure. Fannie Mae's October forecast expects the 30-year rate to average about 7.4% for the rest of 2026 and about 7.5% in 2027. Just one month earlier, it expected about 6.7% for 2027. Forecasts change fast!
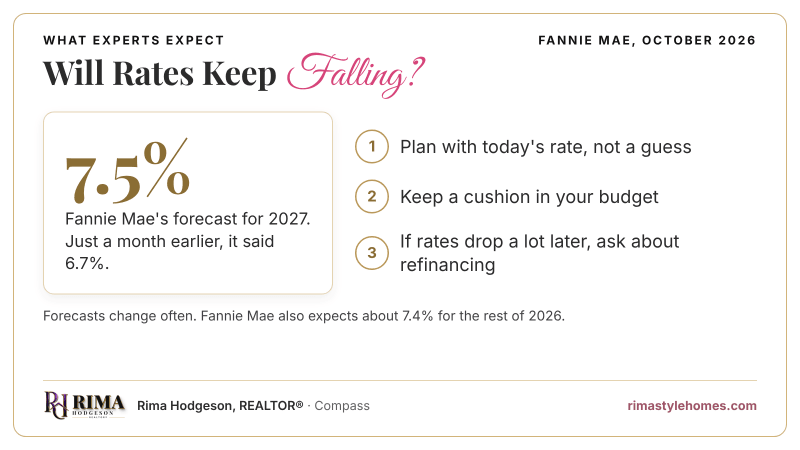
So here's my take: buy when it's right for you, not because of a headline. Plan with today's rate, and keep a cushion in your budget. If rates drop a lot later, ask your lender whether refinancing makes sense. (Refinancing has costs, so it isn't always worth it.)
Buying? 4 Ways to Make the Dip Work for You
What should I do when mortgage rates go down? Here's my game plan:
- Refresh your pre-approval. Your buying power just changed, so ask your lender to update your numbers.
- Compare at least 3 lenders. Rates change every day, so get Loan Estimates on the same day and compare them line by line.
- Ask about a rate buydown. A buydown lowers your rate, either for the first year or two or for the whole loan. A seller credit can help pay for it, and I'll help you ask for one in your offer.
- Check Louisiana down payment help. The Louisiana Housing Corporation's HomeStart programs can help buyers who qualify. I explain them in Do You Really Need 20% Down?
One more trend: adjustable-rate mortgages (ARMs) made up 11.3% of applications in the week ending Oct. 23, the most in more than a year (Mortgage Bankers Association). An ARM can start with a lower rate, but the rate can change later. If you're curious, ask your lender to walk you through the risks.
Selling? Buyers Are Looking Again
Is now a good time to sell my Baton Rouge home? That depends on your goals, but here's some good news: applications to buy a home rose 4% in one week, and overall mortgage applications rose for the first time in nearly two months (Mortgage Bankers Association, week ending Oct. 23). Buyers who were waiting are peeking again.
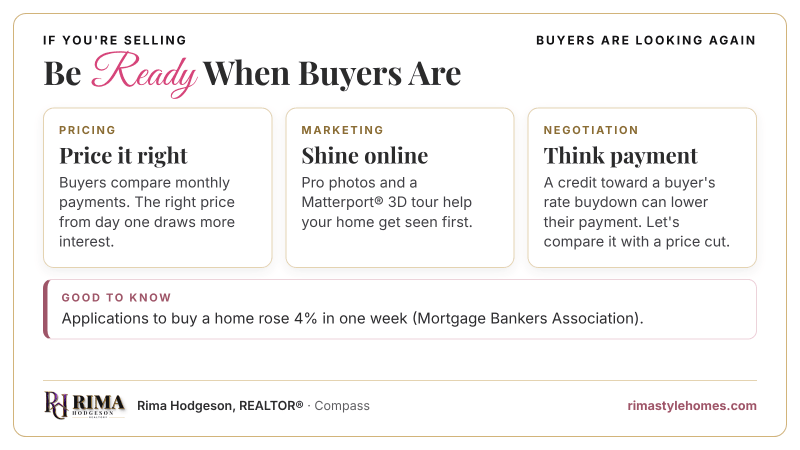
- Price it right from day one. Buyers compare monthly payments, not just prices. The right price draws more interest early.
- Shine online. Pro photos and a Matterport® 3D tour help your home get seen first. When I list a home, all of that is included.
- Think about the payment. A credit toward a buyer's rate buydown can lower their monthly payment. Sometimes that helps more than a price cut, so I'll run both options with you.
Getting ready? Start with Before You List: Do These 5 Things and Skip These 2, then see how I get homes sold.
Questions Buyers Ask Me
What is the mortgage rate in Baton Rouge today?
Freddie Mac's national average for a 30-year fixed was 7.24% on Oct. 29, 2026. Your rate from a Baton Rouge lender can be higher or lower, depending on your credit, down payment, loan type, and points. Ask 3 lenders for quotes on the same day to find your real rate.
Should I wait for mortgage rates to drop before I buy?
It depends on you. Nobody can time rates perfectly, and Fannie Mae expects rates to stay in the 7s through 2027. If you find the right home and the payment fits your budget, waiting may not help. If you're not ready yet, that's OK too.
Is a 15-year mortgage a better deal?
A 15-year loan has a lower rate (6.60% on Oct. 29), and you pay it off twice as fast. But the monthly payment is much higher. On a $242,100 loan, it's about $2,122 a month, compared with about $1,650 for a 30-year loan at 7.24% (principal and interest only).
Does the Fed set mortgage rates?
No. The Federal Reserve sets a short-term rate that banks use to lend to each other. Mortgage rates follow the bond market. The Fed's moves can nudge the bond market, but they don't set your mortgage rate.
Let's Run Your Numbers Together
Whether we find the right home this weekend, next month, or next year, my goal is simply to help you make the best decision for you and your family. And if you're selling, I'll show you what today's buyers can afford in your neighborhood. You are never a transaction to me.
Reach out either way. I'm happy to help.
Call or Text Rima: 225-892-2131 See my buyer plan See my seller plan
More from my blog and website:
- Saving up? Read Do You Really Need 20% Down?
- Making a budget? Here are the home-buying bills nobody warns you about.
- New to buying? Here are the 10 steps I walk you through.
- Comparing parishes? Browse my Baton Rouge area guides.
Where My Info Comes From
I like to give credit where it's due:
- Freddie Mac: Primary Mortgage Market Survey (Oct. 15, 22, and 29, 2026, and the same week in 2025)
- Mortgage Bankers Association: Weekly Applications Survey for the week ending Oct. 23, 2026
- Fannie Mae: Economic and Strategic Research Group, October 2026 Housing Forecast
- Federal Reserve: Federal Open Market Committee statement, Oct. 28, 2026
- Greater Baton Rouge Association of REALTORS® MLS: September 2026 median sale price
- Louisiana Housing Corporation: HomeStart programs
- Homes.com News: "Mortgage rates sink to 7.24%" (Oct. 29, 2026)
Payment examples are principal and interest only and are just for illustration. Your lender will confirm your exact rate and payment. I'm a REALTOR®, not a lender.