

Buying a home is exciting. You find "the one," you picture your couch by the window, and you start counting down to closing day.
But here's a little secret I tell every buyer: your down payment is just the appetizer.
Think of it like a good Louisiana dinner. The appetizer is just the start, and there are a few more things on the menu. None of them are scary when you know they're coming. It's the surprise that stings! So let's take the surprise out of it, one bill at a time, in plain words.
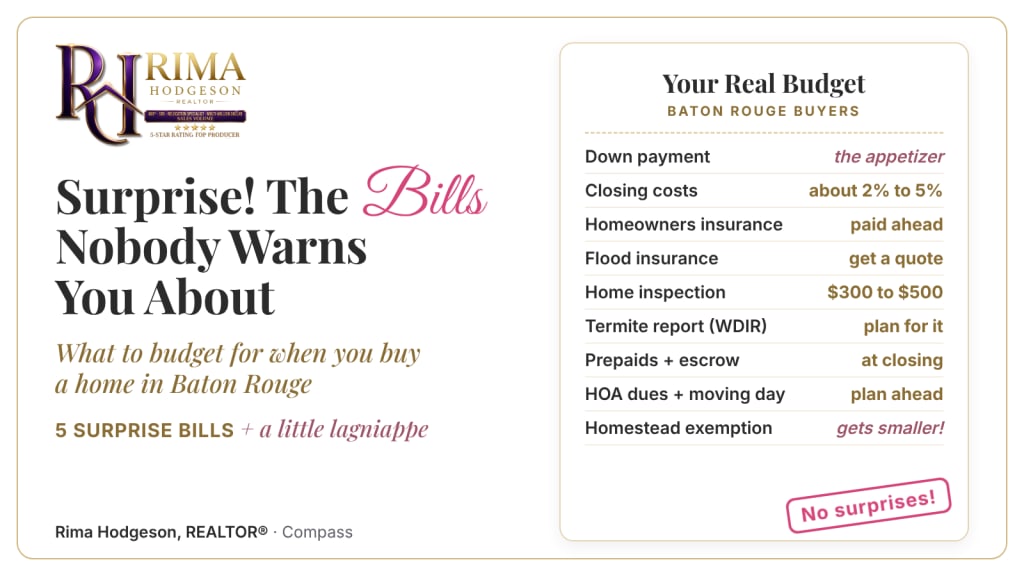
The quick answer: Besides your down payment, plan for closing costs (about 2% to 5% of the price), homeowners insurance, maybe flood insurance, inspections, prepaids and escrow, HOA dues, and moving day. And save room for the lagniappe at the end: a bill that gets smaller!
Jump to a surprise:
#1 Closing costs #2 Insurance #3 Flood #4 Inspections #5 Escrow + little bills Lagniappe
Surprise Bill #1: Closing Costs
How much are closing costs in Baton Rouge? Here's the easy math:
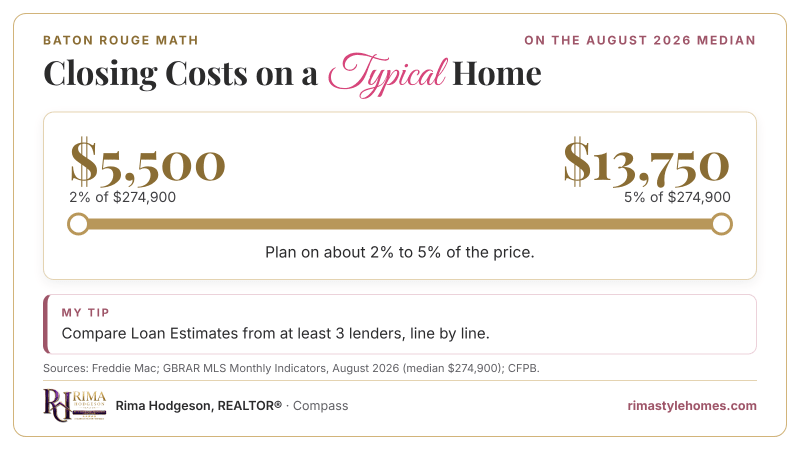
- Freddie Mac says to plan on about 2% to 5% of the price.
- In August 2026, the typical (median) home in the Greater Baton Rouge area sold for $274,900, according to the Greater Baton Rouge Association of REALTORS® (GBRAR).
- On that price, closing costs come to about $5,500 to $13,750.
So what's in there? Lender fees, the appraisal, a credit report, title insurance, and government fees. Your exact number depends on your loan, your lender, and the home you pick.
My tip: Get a Loan Estimate from at least 3 lenders and compare them side by side. (The Consumer Financial Protection Bureau suggests this too.) About 3 business days before closing, you'll get your Closing Disclosure. Bring it to me, and we'll go over it line by line.
Good news: Sometimes the seller can help pay closing costs. Homes in the Baton Rouge area took about 70 days to sell in August (GBRAR), so there's often room to ask. Asking is part of my job when I negotiate for you.
Surprise Bill #2: Homeowners Insurance (Hello, Hurricane Deductible!)
Your lender will want proof of homeowners insurance before closing. And here's the surprise: you'll usually pay the first 6 to 12 months up front, at or before closing (that's from the Consumer Financial Protection Bureau).
Here in Louisiana, ask about the hurricane deductible. It's usually a percentage, not a flat dollar amount. The Louisiana Department of Insurance says it's often 2% to 5% of the home's insured value. Here's what that looks like:
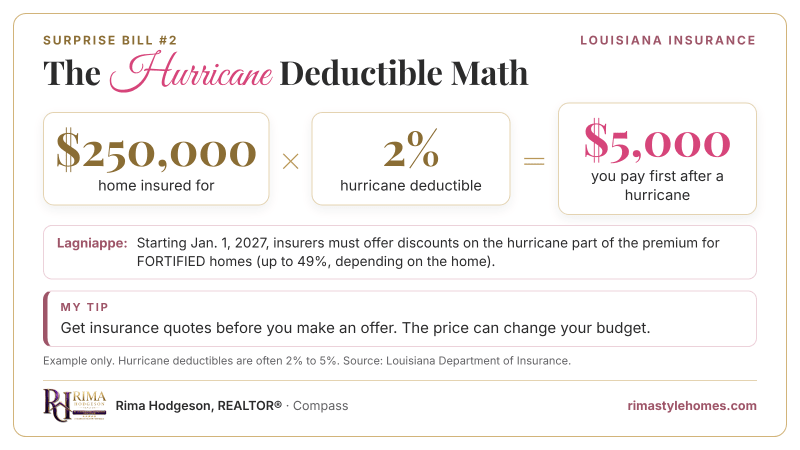
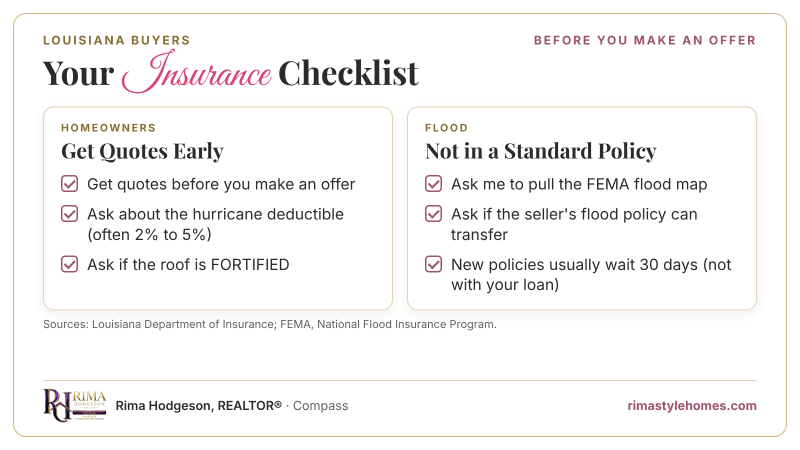
My tip: Get insurance quotes early, before you make an offer if you can. The price can change how much house feels comfortable.
Lagniappe: ask about a FORTIFIED roof. Starting January 1, 2027, Louisiana insurers must offer discounts on the hurricane part of the premium for FORTIFIED homes. The discount can be up to 49%, depending on where the home is and its FORTIFIED level (Louisiana Department of Insurance). The state's Louisiana Fortify Homes Program has also offered grants of up to $10,000 to upgrade roofs. Love a house? I'll ask if its roof is FORTIFIED.
Surprise Bill #3: Flood Insurance
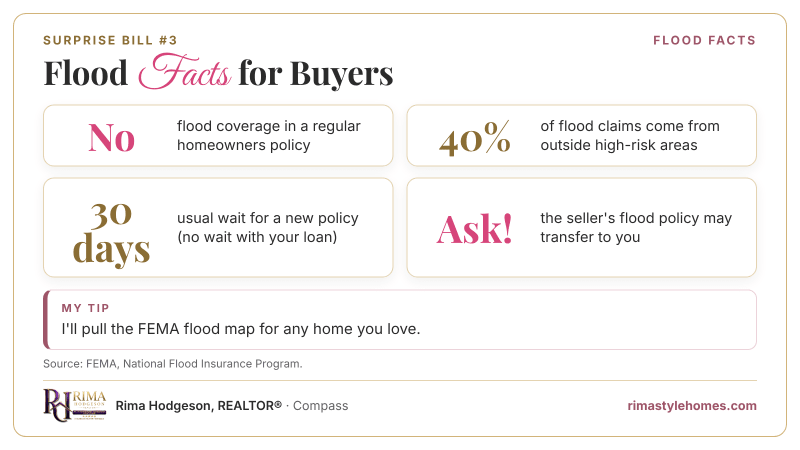
This one surprises a lot of people: a regular homeowners policy doesn't cover floods.
- If the home is in a high-risk flood area and you have a government-backed loan, your lender will usually require flood insurance.
- But don't stop there. FEMA says about 40% of flood insurance claims come from outside high-risk flood areas.
Here's what I do for you:
- I'll pull the FEMA flood map for any home you love.
- I'll ask the seller about their flood policy. FEMA says a seller's policy can often transfer to the new owner, so the coverage keeps going.
- We'll get a flood quote while you're shopping, not after you're under contract.
Good to know: A new flood policy usually has a 30-day wait before it starts. That wait doesn't apply when you buy the policy as part of getting your home loan.
Surprise Bill #4: Inspections (Yes, Termites Too)
A home inspection is one of the best deals in real estate. Freddie Mac puts the cost at about $300 to $500. In Louisiana, home inspectors are licensed by the Louisiana State Board of Home Inspectors.
You'll also want a termite inspection. Here, the report for a home sale is called a WDIR (Wood Destroying Insect Report), and a licensed termite company does it. Depending on the home, you might add a few extra checks, like the roof, the sewer line, or the heating and air.
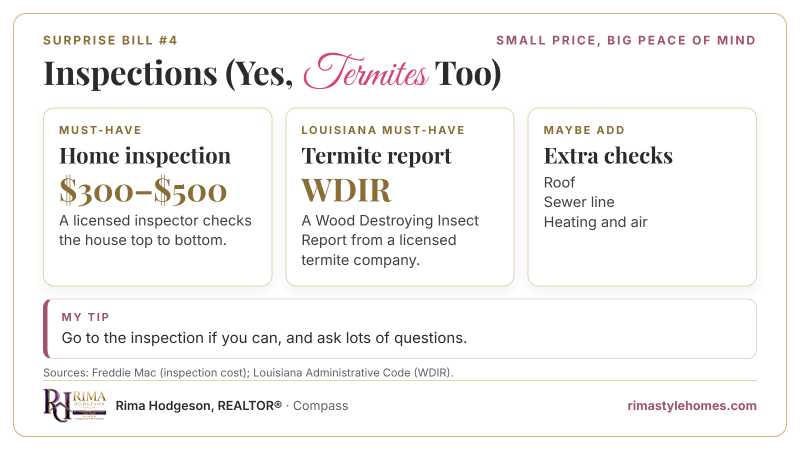
My tip: Small price, big peace of mind. Go to the inspection if you can, and ask lots of questions.
Surprise Bill #5: Prepaids, Escrow, and the Little Bills
Prepaids are costs you pay ahead at closing: property taxes, homeowners insurance, and the interest until your first payment is due (Consumer Financial Protection Bureau).
Escrow sounds fancy, but it's simple. If your lender sets one up, a little of each monthly payment goes into it. Then your lender pays your property taxes and insurance for you. You'll put in a starting balance at closing.
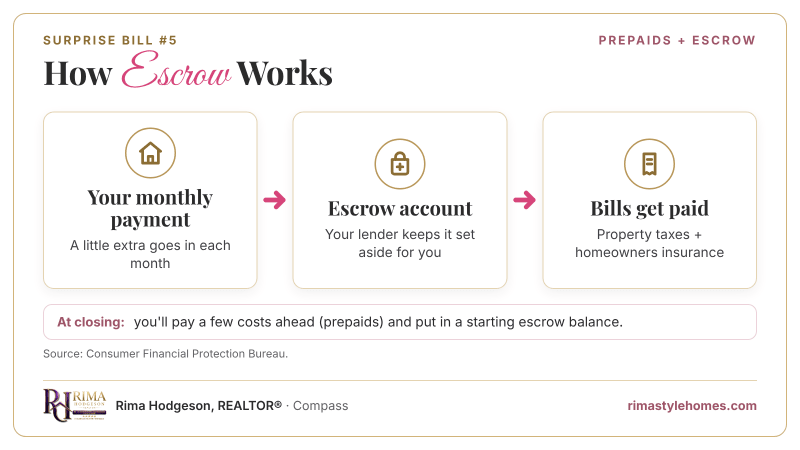
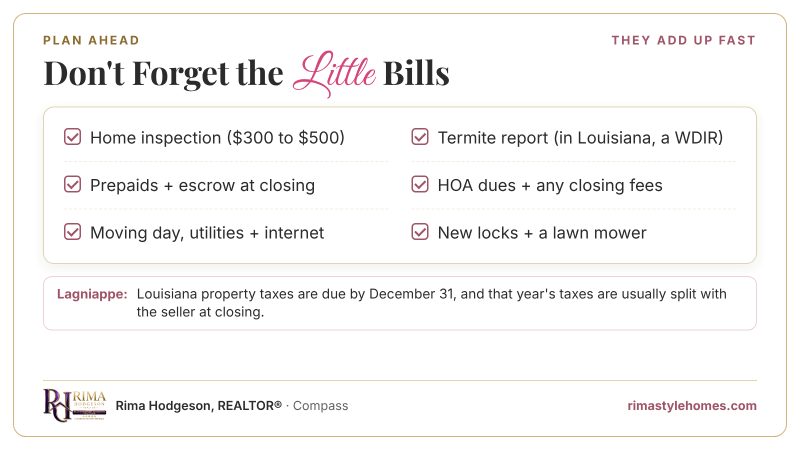
The Louisiana twist: Property taxes here are due by December 31 for the year. At closing, that year's taxes are usually split between you and the seller, based on the closing date (Louisiana House Fiscal Division).
And the little bills that sneak up on you:
- HOA dues: If the neighborhood has a homeowners association, ask about the dues and any fees due at closing.
- Moving day: a truck or movers, boxes, and setting up your utilities and internet.
- Move-in must-haves: new locks, a few small fixes, and maybe a lawn mower. Louisiana grass grows fast!
Lagniappe: A Bill That Gets Smaller!
Here's the sweet ending. After you close, file for your homestead exemption with your parish assessor. In Louisiana, it covers the first $75,000 of your home's market value for most property taxes. It doesn't apply to city taxes, except in Orleans Parish (Louisiana House Fiscal Division).
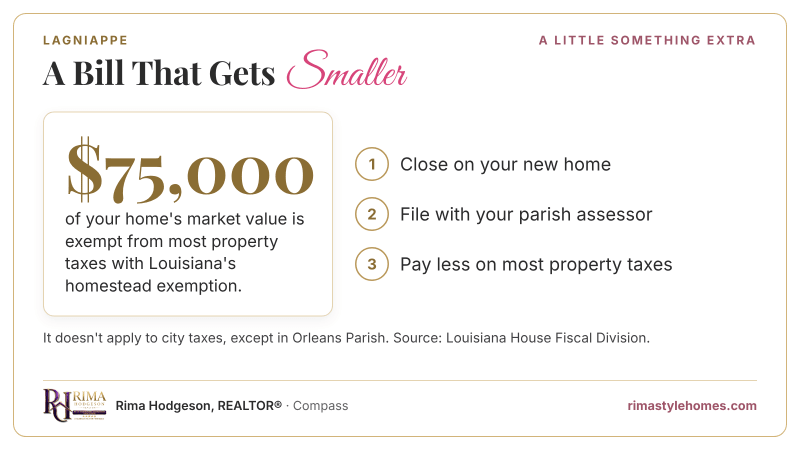
It's one of the easiest ways to lower your tax bill, and it's easy to forget in all the fun of moving in. Put it on your list for right after closing day!
Questions Buyers Ask Me
How much money do I need to buy a home in Baton Rouge?
Plan for your down payment plus closing costs, which Freddie Mac puts at about 2% to 5% of the price. Then add insurance, prepaids, inspections, and moving costs. Some buyers qualify for help, too. The Louisiana Housing Corporation has programs for eligible first-time buyers. Ask me, and we'll look into it together.
Can the seller pay some of my closing costs?
Sometimes, yes. It's part of your offer, and your loan type sets limits on how much. We'll talk it over with your lender before we write the offer.
Do I need flood insurance if the home isn't in a high-risk flood zone?
Your lender may not require it, but it's worth getting a quote. FEMA says about 40% of flood insurance claims happen outside high-risk flood areas.
How do I file for the homestead exemption?
Contact your parish assessor's office after you close. They'll tell you what to bring and how to apply.
Let's Build Your Budget Together
Knowing these numbers early makes the whole process feel calmer. I'll help you map out your budget and go over every line before closing. No surprises, just a plan that fits you.
Call or Text Rima: 225-892-2131 See my buyer plan
More from my blog:
- New to all this? Start with the 10 steps I walk you through.
- Before you fall for a street, read 7 neighborhood clues first-time buyers miss.
- Exploring areas? Browse my Baton Rouge area guides.
- Selling first? Here's my seller plan.
Reach out either way. I'm happy to help.
Where My Info Comes From
I like to give credit where it's due. Here's where these numbers and tips come from:
- Freddie Mac: closing costs (2% to 5% of the price) and home inspection costs ($300 to $500)
- Greater Baton Rouge Association of REALTORS® (GBRAR), MLS Monthly Indicators, August 2026: the $274,900 median sale price and about 70 days to sell
- Consumer Financial Protection Bureau (CFPB): Loan Estimates, the Closing Disclosure, prepaids, and insurance paid at closing
- Louisiana Department of Insurance: hurricane deductibles, FORTIFIED roof discounts, and the Louisiana Fortify Homes Program
- FEMA, National Flood Insurance Program: flood claims, policy transfers, and the 30-day wait
- Louisiana House Fiscal Division, Louisiana Property Tax Basics: the homestead exemption and property tax due dates
- Louisiana Housing Corporation: programs for first-time homebuyers
- Louisiana State Board of Home Inspectors and the Louisiana Administrative Code: home inspector licensing and the WDIR